ITAT Grants Relief on Section 87A Tax Rebate for Short-Term Capital Gains, But a Catch Applies
· GlobeWire Daily Editorial Desk · Source: timesofindia.indiatimes.com
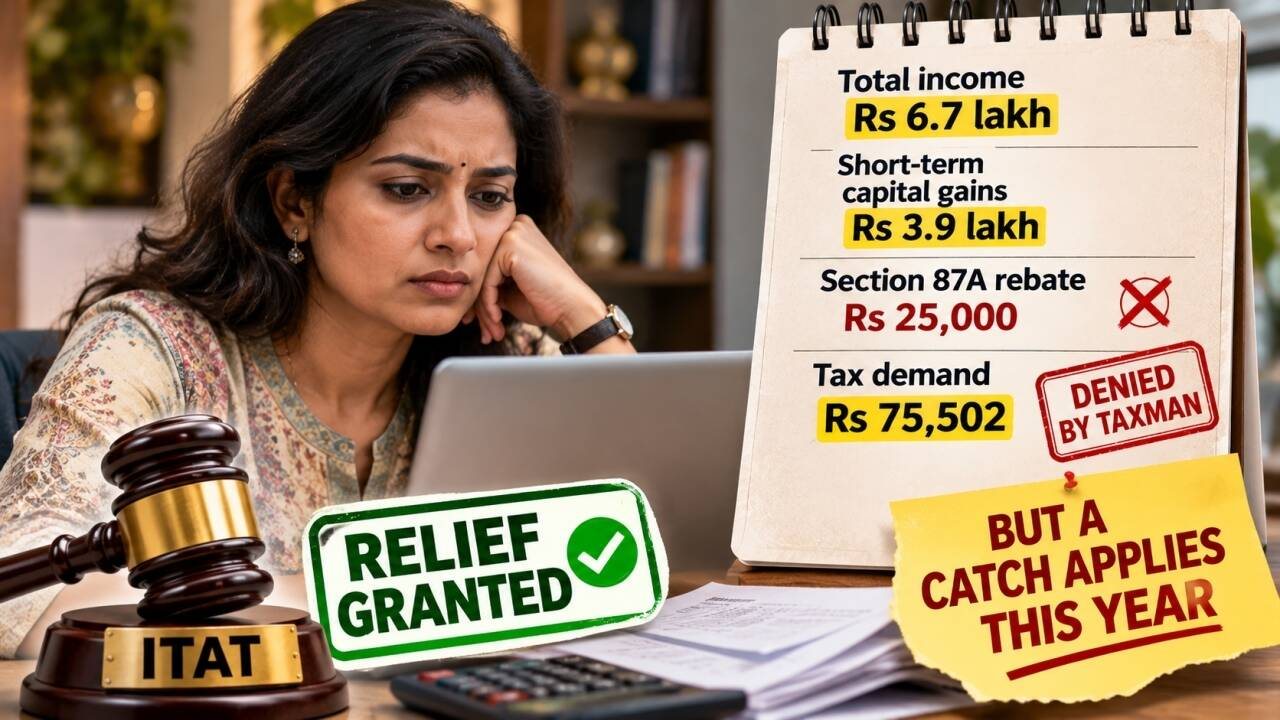
A taxpayer has successfully contested an income tax rebate denial at the Income Tax Appellate Tribunal (ITAT), Hyderabad, concerning short-term capital gains from listed equity shares.
Case Background
For the assessment year 2025-26, a female taxpayer declared a total income of Rs 6,77,511, which included Rs 3,97,511 in short-term capital gains taxable under Section 111A of the Income-tax Act, 1961. Opting for the new tax regime under Section 115BAC(1A), she claimed a Rs 25,000 rebate under Section 87A.
The Centralised Processing Centre (CPC) in Bengaluru calculated her tax payable at Rs 75,502 without granting the rebate. After the Commissioner of Income Tax (Appeals) upheld the denial, she appealed to the ITAT Hyderabad bench.
Tribunal Ruling
The ITAT ruled in favor of the assessee on November 6, 2026. The tribunal found that neither Section 87A nor Section 115BAC(1A) expressly barred the rebate merely because part of the income was taxable under Section 111A at a special rate. The bench noted that administrative circulars or return-filing utilities cannot override clear statutory provisions.
Important Caveat for Future Years
Experts note that while the ruling offers clarity for past assessments, the position changes going forward. The Finance Act, 2025 has expressly restricted the Section 87A rebate to tax calculated at specified slab rates, meaning the rebate will no longer apply against special-rate income like Section 111A short-term capital gains from FY 2025-26 onwards.
- Check official ITAT orders or consult a certified tax professional to verify individual tax liabilities.
- Review current tax regulations and Finance Act amendments before claiming rebates on special-rate incomes.
More to read
 JP Morgan Chief Jamie Dimon Plans to Offset Planned UK Bank Tax Surcharge Increase
 From Jobseeker to Fixed-Term Contract: Why Finding Work Hasn't Ended Financial Precariousness
 India on Track to Reach $1 Trillion Exports This Year, Says Commerce Secretary
 IBM Reports $3 Billion Annual India Investment and Outlines Global Quantum Plans