Smart Ways to Manage and Allocate Your Diwali Bonus, According to Financial Experts
· GlobeWire Daily Lifestyle Desk · Source: www.bhaskar.com
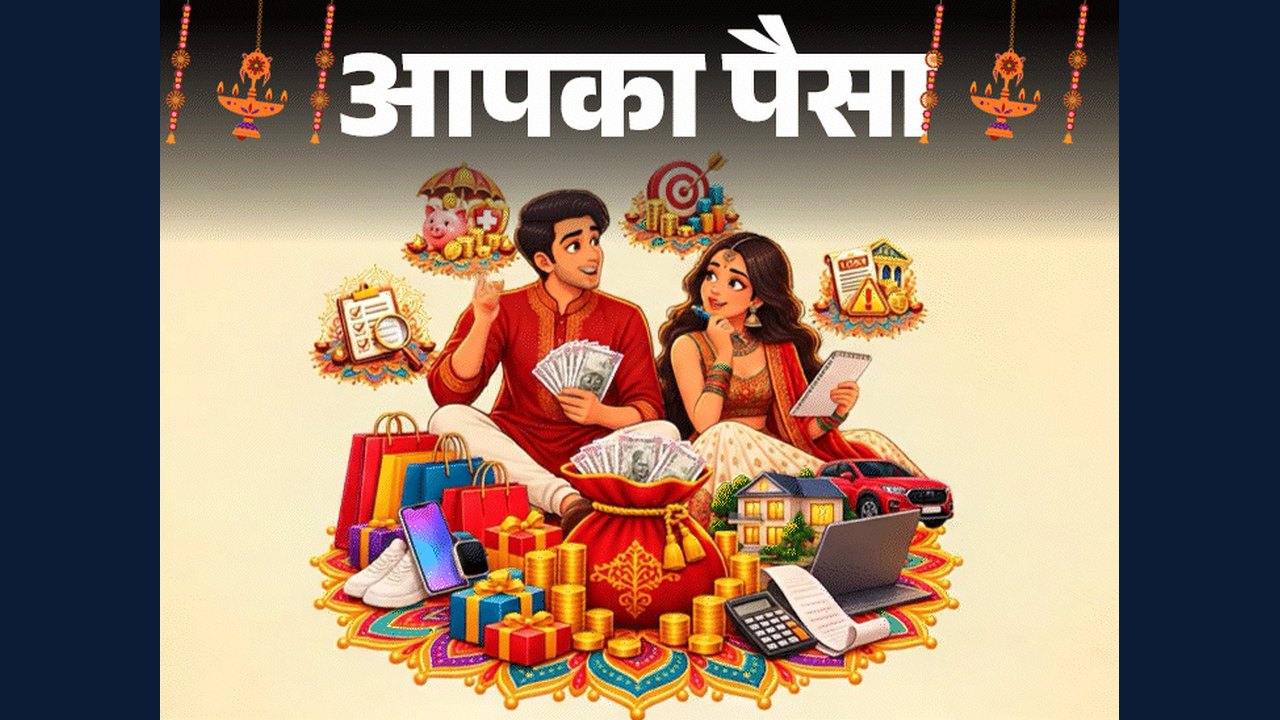
Image: अदिति ओझा · Photo source · Resized and letterboxed to 16:9; no AI generation
Receiving a Diwali bonus is often viewed as a welcome financial windfall, but deciding how to allocate it requires careful thought. Financial advisors suggest that rather than spending the entire extra income on festive shopping, individuals should evaluate their current financial standing to balance enjoyment, savings, and debt reduction.
Financial planning experts note that managing a bonus effectively depends on personal circumstances, such as whether an emergency fund exists or if high-interest debt needs to be cleared. According to guidelines discussed by financial advisors, structured budgeting concepts like the 70:20:10 rule can serve as a helpful framework, though not a rigid mandate.
Practical Steps for Bonus Allocation
- Assess Existing Liabilities: Prioritize paying off high-interest debts, such as credit card balances or personal loans, to reduce future interest burdens.
- Build an Emergency Fund: If savings are lacking, allocate a portion of the bonus toward building a safety net that covers three to six months of essential living expenses, including rent, utilities, and EMIs.
- Set Financial Priorities: Ask key questions about upcoming expenses in the next 6 to 12 months before committing funds to volatile investments.
Choosing Between Savings and Investments
- Short-Term Needs: If money might be needed soon, keep funds in accessible options like savings accounts or short-term fixed deposits rather than market-linked instruments.
- Long-Term Goals: If emergency funds are sufficient and debts are managed, individuals may consider long-term options like PPF or NPS, keeping lock-in periods and withdrawal rules in mind.
Verification and Best Practices
Readers can verify financial planning concepts by consulting certified financial advisors and reviewing official tax guidelines regarding employer-provided bonuses, which are typically treated as taxable salary income depending on individual tax brackets.
AI-assisted reporting; source claims are attributed and have not been independently verified.
More to read
 Smart Ways to Manage and Plan Your Diwali Bonus: Expert Financial Tips
 Simple Ways to Elevate Your Midweek Pasta, According to Julia Busuttil Nishimura
 Can Red Light Improve Your Sleep? What Experts Say About the Wellness Trend
 Nine Budget-Friendly Ways to Wear Autumn/Winter 2026 Catwalk Trends, According to The Guardian
Trending on GlobeWire Daily
Selected from recent coverage and related topics; not live search rankings.
 Madhya Pradesh Government Plans Revenue Generation from 117-Year-Old Edward Villa in Mumbai Through Leasing
 iPhone 18 Pro Named TechRadar Product of the Year 2026
 Google Project Suncatcher Runs Gemma 4 AI on Orbiting Satellite and Receives First Response
 Gender Disparities in Eye Care Access Across India Examined
 Satellite Images Show Cyclone Arnab Weakening Over India As New System Brews
 Expanding Green and Blue Spaces Crucial for India's Economic and Public Health, Reports Indicate